OC Grant Accountants and Advisory | Tax + Super | June 2026
This overview reflects the original newsletter. Tax and superannuation rules may have changed since publication.
Explore the Budget proposals discussed in June, including negative gearing, CGT and discretionary trusts, plus super access and bankruptcy considerations.
Negative gearing after the Budget
The June newsletter examines the negative gearing proposals announced in the May Budget, focusing on residential investment property and the importance of acquisition dates.
The source article discusses transitional treatment for existing and newly acquired property, the proposed treatment of rental losses and the distinction between residential property and other investments. It also notes that the details were subject to consultation and legislation at the time.
Proposed changes to the CGT discount
A companion feature explores the proposed move from the CGT discount to an indexed cost base approach, alongside a minimum tax rate. It considers assets bought and sold on different sides of the proposed changeover date.
Valuation evidence, asset holding periods and sale timing all feature in the discussion. The article is a record of the proposals described in June 2026 and should not be read as a substitute for checking the final rules.
Discretionary trusts and small business
The issue also considers the proposed minimum tax on discretionary trust income and what it could mean for family businesses. It discusses distributions, corporate beneficiaries and the potential cost of changing a business structure.
The newsletter is explicit that these trust measures were not yet law when the article was written. Its central planning message is to assess a structure in the context of the business, its owners and the eventual legislation before making changes.
JobSeeker and access to super
For people who have stopped working in their early 60s, the interaction between JobSeeker requirements and superannuation release conditions can be complicated. The June issue explores why the date employment ended and a person’s intentions about future work may matter.
It also discusses alternative pathways that may need to be considered, including transition-to-retirement income streams and financial hardship provisions. Eligibility and the potential effect on benefits require an individual assessment.
Superannuation and bankruptcy
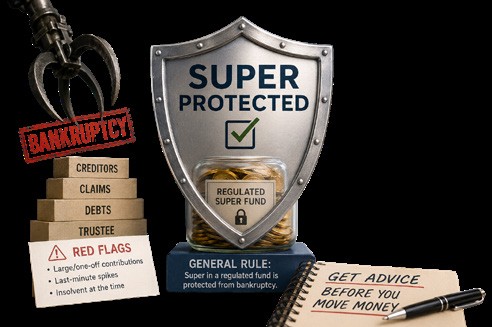
The final article considers how super can be treated in bankruptcy, including the distinction between funds held in super, withdrawals and pension income. It also discusses contributions made with the intention of keeping money away from creditors.
The newsletter highlights the importance of timing and trustee responsibilities, particularly for SMSFs. Moving money or changing a pension arrangement can have consequences beyond bankruptcy, so the article encourages advice before action.
Talk to OC Grant
If a topic in this issue relates to your business, property or retirement plans, contact OC Grant Accountants and Advisory on (07) 3522 2400 or email [email protected] to discuss your circumstances.
Adapted from the OC Grant June 2026 client newsletter. © Content in partnership with the Institute of Financial Professionals Australia.
General information only. This content has been prepared without taking into account your objectives, financial situation or needs. Before acting, consider whether it is appropriate for your circumstances and seek professional advice.